The Jakarta Post
Please Update your browser
Your browser is out of date, and may not be compatible with our website. A list of the most popular web browsers can be found below.
Just click on the icons to get to the download page.
Popular Reads
Top Results
No results found. Please check your search term and try again
Can't find what you're looking for?
View all search results
Popular Reads
Top Results
No results found. Please check your search term and try again
Can't find what you're looking for?
View all search resultsHas Indonesia’s stock market really changed?
Indonesia’s reforms have improved transparency and regulation, but their impact remains constrained by structural problems that stricter rules alone cannot resolve.
Change text size
Gift Premium Articles
to Anyone
Share the best of The Jakarta Post with friends, family, or colleagues. As a subscriber, you can gift 3 to 5 articles each month that anyone can read—no subscription needed!
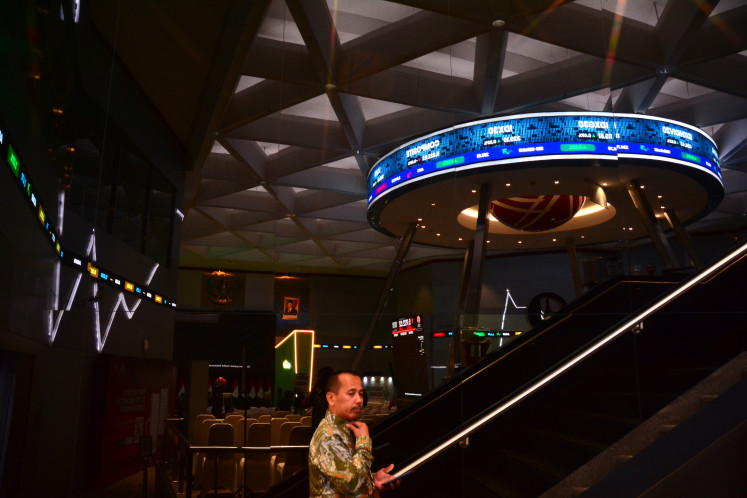
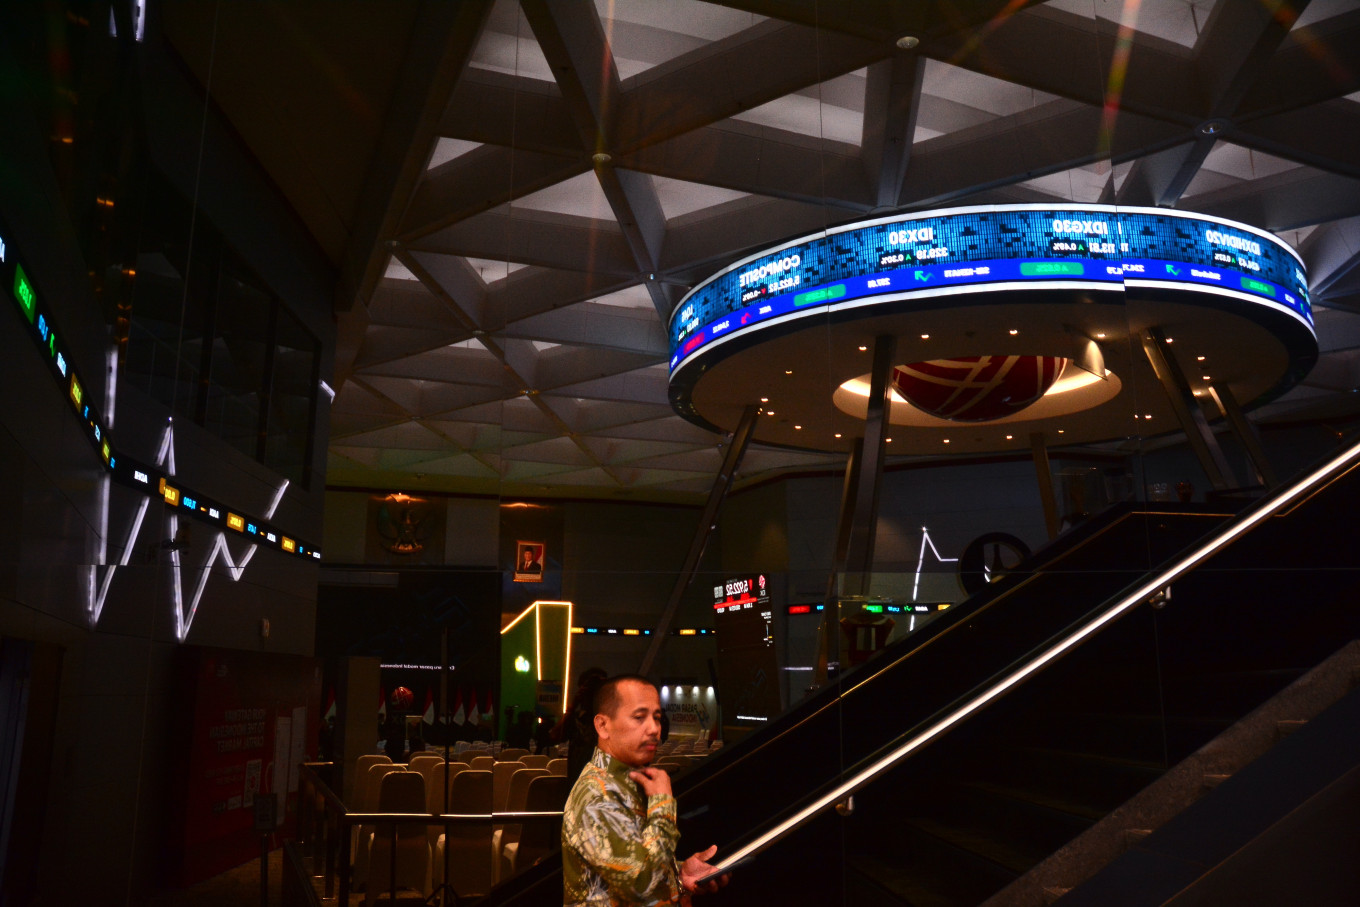 A man uses his mobile phone in front of a reflection of an electronic board displaying stock prices on Oct. 14 at the Indonesia Stock Exchange (IDX) building in South Jakarta. (JP/Iqro Rinaldi)
I
ndonesia’s stock market plunged 11.57 percent on Friday after MSCI proposed reclassifying the country from an Emerging Market to a Standalone Market, triggering a trading halt. In January, MSCI’s earlier warning about ownership transparency and suspected coordinated trading also triggered a sharp sell-off, sending the market down 16.7 percent over two days.
Between these two episodes, Indonesian regulators have introduced a series of reforms aimed at restoring market confidence. Despite the reforms, the market now faces an even more serious threat. Why?
Indonesia’s reforms have improved transparency and regulation, but their impact remains constrained by concentrated ownership, limited institutional demand and uneven liquidity — structural problems that stricter rules alone cannot resolve. MSCI’s proposed market-wide downgrade also risks treating companies with different investment characteristics alike.
Indonesia needs credible enforcement and more differentiated treatment of securities, alongside sustained efforts to deepen the market.
Since January, the Financial Services Authority (OJK), Indonesia Stock Exchange (IDX) and central securities depository (KSEI) have expanded disclosures of shareholdings above 1 percent, refined investor classifications and introduced the High Shareholding Concentration (HSC) framework. They have also established a phased roadmap to raise the minimum free float from 7.5 to 15 percent.
Although these measures have improved investor access to information and strengthened the ability to identify ownership concentration and potential market risks, the results remain less convincing. MSCI continues to report investor concerns about suspected coordinated trading and the absence of convincing evidence of meaningful enforcement.

OJK’s Oct. 16 announcement of sanctions against beneficial owners and other parties linked to shares of three listed companies is an important development, but restoring confidence requires consistent enforcement rather than isolated actions. Better disclosure cannot substitute for credible action against misconduct.
Your Opinion Matters
Share your experiences, suggestions, and any issues you've encountered on The Jakarta Post. We're here to listen.
Enter at least 30 characters
0
/ 30
Thank you
Thank you for sharing your thoughts. We appreciate your feedback.